
Changing auto insurance providers can seem straightforward when a new quote comes in at a lower price. However, the premium is only one part of an insurance policy. Differences in coverage, deductibles, optional protection, service, and cancellation terms can all affect whether a new policy is actually a good fit.
For drivers comparing auto insurance in Ontario, the goal should be to understand exactly what will change before making a decision. A careful comparison can help reveal whether a lower premium represents genuine savings or simply reflects different coverage.
Compare the Same Coverage Before Comparing Price
Two insurance quotes can look similar while providing different levels of protection. Before focusing on the total premium, drivers should check that they are comparing policies on equivalent terms.
Start with liability limits and the main types of coverage included in each quote. Then look at deductibles, which determine how much the policyholder may need to pay toward certain covered claims. A higher deductible can reduce the premium, but it may also increase the driver’s out-of-pocket expense following a loss.
Optional coverage deserves the same attention. A current policy may include protections or endorsements that are absent from a new quote. Conversely, a new quote may include options that are not necessary for a particular driver.
Vehicle information and use should also be consistent. The same drivers, vehicles, annual distances, commuting patterns, and other relevant details should be reflected in each quote. Otherwise, a price comparison may not provide an accurate picture.
The practical question is not simply, “Which policy costs less?” It is, “What coverage am I receiving for the price?”
Review How the Policy Fits Your Current Driving Needs
Insurance needs can change over time. A move, a new vehicle, a different commute, or changes in the people who regularly drive the vehicle can affect what a household needs from its policy.
Before switching auto insurance providers, it can be useful to review the existing policy as if purchasing coverage for the first time. Confirm that the listed drivers and vehicles are accurate and that the insurer has current information about how each vehicle is used.
Drivers should also consider whether their existing deductibles still make sense for their financial situation. A deductible that seemed reasonable several years ago may no longer be the preferred choice. The same applies to optional coverage.
This review helps separate two decisions that can otherwise become mixed together: whether the current coverage remains suitable and whether another provider offers a better fit. Changing car insurance is an opportunity to reconsider both questions rather than simply transferring an old arrangement to a new insurer.
Consider Service and Claims Support
Price and coverage are easier to compare than service, but service can become particularly important when a driver needs to make a policy change or report a claim.
Before choosing a provider, consider how policy questions and claims are handled. Drivers may want to understand who they would contact after a collision, what options are available for submitting information, and how easily they can reach someone when they need assistance.
It is also worth considering routine service. Adding a vehicle, changing an address, updating drivers, or requesting insurance documents are common tasks. The ability to handle these changes efficiently can influence the overall experience of maintaining a policy.
No provider can guarantee how every future claim will unfold. Still, understanding the available service channels and claims process gives drivers another useful point of comparison beyond the annual premium.
Check Cancellation Terms and Effective Dates
Timing matters when changing providers, particularly if the switch happens before an existing policy reaches its renewal date.
Drivers should review the cancellation terms of their current policy before ending it. Depending on the circumstances and policy terms, cancelling before renewal may have financial implications. Knowing these details in advance makes it easier to determine the actual cost of making a change.
The effective date of the replacement policy also requires careful attention. The new coverage should be confirmed before the old policy ends. Even an unintended coverage gap can create complications for a driver who needs continuous protection.
Documentation should be reviewed carefully rather than relying only on a quote or preliminary discussion. Drivers should confirm when the new policy becomes effective and when the previous policy will terminate. Keeping records of these dates can help prevent misunderstandings during the transition.
Look at the Full Policy, Not Just the Quoted Premium
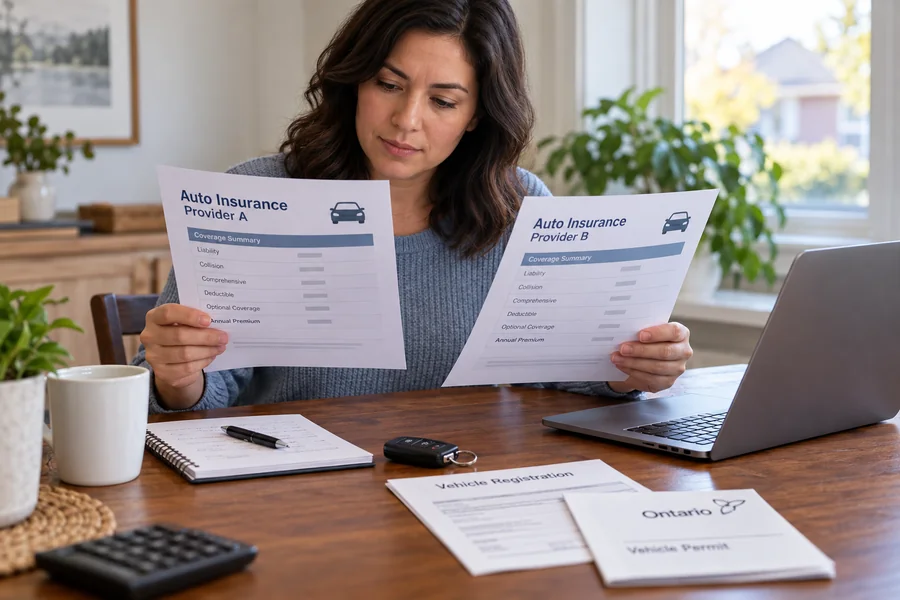
Once the main details are gathered, compare the current policy and proposed replacement side by side. Review liability limits, deductibles, optional coverage, vehicle use, listed drivers, and other relevant terms before deciding whether the quoted price represents comparable protection.
Ontario drivers who want additional information while reviewing these factors can consult Jeffery & Spence auto insurance resources when considering their current protection and other available options.
The purpose of this comparison is not to assume that staying or switching is automatically the better choice. A lower premium may be worthwhile when coverage remains appropriate, while a higher quote could include protections or terms that better suit a driver’s circumstances.
For consumers evaluating car insurance in Ontario, the strongest decision is an informed one. Understanding what is being gained, removed, or changed makes it easier to judge a policy on its overall value rather than price alone.
Before cancelling an existing policy, drivers should have the replacement coverage confirmed, understand any cancellation implications, and verify the effective dates. Taking the time to check those details can make switching providers a deliberate financial decision rather than simply a reaction to a new quote.
